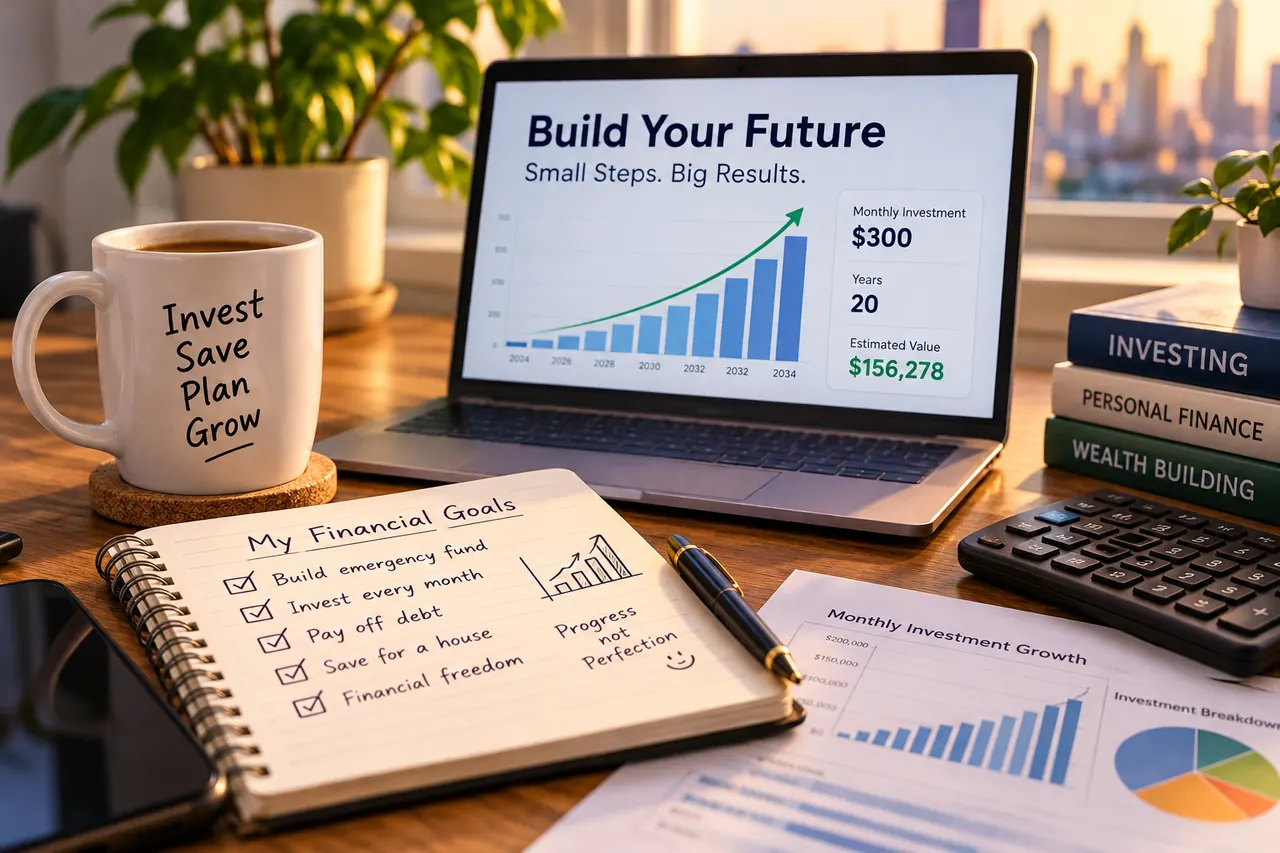
Choose a monthly investment amount from money left after household bills, required debt payments and near-term cash needs. In the worked $4,000 take-home budget below, $300 remains for additional investing. That is an affordability example, not a recommended contribution for every reader; payroll retirement deductions must be tracked separately.
How Much of Your Income Should You Invest?
There is no single percentage that works for everyone. A 10% to 15% contribution is used below only as a percentage-to-dollars illustration, including any employer contribution in the total you choose to measure. It is not a retirement recommendation or a claim that this range will fund your goals.
For example, someone earning $60,000 annually would calculate $6,000 to $9,000 per year at an illustrative 10% to 15% rate, before checking affordability and individual retirement needs.
That works out to approximately $500 to $750 per month.
However, someone with expensive credit card debt or no emergency savings may need to prioritize those needs before increasing investments.
The best monthly amount is one you can maintain without missing essential bills or relying on new debt.
How to Calculate Your Monthly Investment Budget
Start with your actual monthly take-home pay rather than assuming you can invest a fixed percentage of your salary.
Subtract essential expenses, minimum debt payments, and the money you need for short-term goals.
Then decide how much of the remaining amount can be invested consistently. Use our monthly budget guide to calculate that surplus, and our monthly savings guide to separate cash savings from investment contributions.
If a traditional or Roth 401(k) contribution has already been deducted from your paycheck, do not subtract it again from deposited take-home pay. The remaining surplus represents money available for additional investing. When tracking total retirement contributions, record payroll contributions separately and distinguish your own contributions from any employer match; employer matching funds are not cash available for household bills.
Example: A $4,000 Monthly Take-Home Paycheck
| Monthly Budget Category | Amount |
|---|---|
| Take-home pay | $4,000 |
| Housing and utilities | $1,500 |
| Groceries and transportation | $700 |
| Insurance and other essentials | $400 |
| Debt payments | $350 |
| Emergency fund savings | $300 |
| Other spending | $450 |
| Available for investing | $300 |
In this example, the person has $300 per month available to invest without reducing the amounts already allocated to bills, debt, and emergency savings.
This is only an illustration. Your actual investment budget could be higher, lower, or zero depending on your circumstances.
What Happens If You Invest $100, $300, or $500 Monthly?
Consistent contributions can become meaningful over long periods because investment returns may compound.
The table below assumes contributions made at the end of each month, a hypothetical nominal annual return of 7% divided by 12 and compounded monthly, and no starting investment. Values are rounded to the nearest dollar.
| Monthly Investment | After 10 Years | After 20 Years |
|---|---|---|
| $100 | $17,308 | $52,093 |
| $300 | $51,925 | $156,278 |
| $500 | $86,542 | $260,463 |
These figures are hypothetical illustrations, not forecasts or guaranteed returns. They exclude taxes, fees, and inflation. Actual market returns fluctuate, and investments can lose value.
For example, investing $300 each month for 20 years means contributing $72,000 of your own money. Under the hypothetical assumptions above, the ending balance would be approximately $156,278.
The difference comes from assumed investment growth over time.
Should You Invest or Build an Emergency Fund First?
Before investing aggressively, consider whether you have enough cash available for unexpected expenses.
An emergency fund can help cover situations such as medical bills, car repairs, or job loss without forcing you to sell investments during a market decline.
The Consumer Financial Protection Bureau recommends establishing emergency savings based on your own financial circumstances.
You do not necessarily have to finish building a large emergency fund before investing anything. Some households can contribute to both goals simultaneously, especially when an employer offers a retirement-plan match.
The important point is to avoid investing money you may need immediately. Our emergency fund guide explains how to calculate a cash reserve from essential expenses.
What About High-Interest Debt?
High-interest credit card debt can make investing more difficult.
For example, carrying a credit card balance with a 24% annual interest rate while hoping to earn 7% from investments creates a difficult trade-off. Paying down expensive debt provides a predictable reduction in interest costs, while investment returns are uncertain.
If you have high-interest debt, consider prioritizing repayment while maintaining essential savings and reviewing any employer retirement matching benefits.
Where Can Beginners Invest Each Month?
Several account types may be relevant to U.S. investors.
Employer-Sponsored 401(k)
A workplace 401(k) allows eligible employees to save for retirement through payroll deductions. Some employers also contribute matching funds.
Check your plan’s rules, investment options, fees, and vesting schedule.
Individual Retirement Account (IRA)
A traditional or Roth IRA may offer tax advantages depending on your eligibility and circumstances.
Contribution limits and income restrictions can change, so check current IRS guidance before contributing.
Taxable Brokerage Account
A taxable brokerage account may provide more flexibility for goals outside retirement accounts, although investment income and gains may create tax obligations.
Whatever account you choose, understand the investments you purchase, the fees involved, and the risks.
How to Start Investing With a Small Amount
If your budget allows only $25 or $50 per month, that can still be a reasonable starting point.
A practical approach is to select a manageable amount, automate contributions if appropriate, and review your budget periodically.
You can increase contributions when your income rises, debt payments decrease, or your emergency savings become more secure.
Avoid investing money needed for next month’s rent, groceries, or other essential expenses.
Common Mistakes to Avoid
One mistake is choosing an investment amount based on an optimistic budget rather than actual spending.
Another is assuming the stock market will deliver the same return every year. Even diversified portfolios can experience significant declines.
Also, avoid overlooking investment fees, taxes, and the possibility that inflation will reduce future purchasing power.
A sustainable plan should account for uncertainty rather than depend on perfect market conditions.
Frequently Asked Questions
Is $100 a month enough to start investing?
It can be. Whether $100 is appropriate depends on your expenses, debts, savings, and financial goals. Consistency matters more than choosing an impressive starting amount.
Should I invest 20% of my income?
Not necessarily. A 20% contribution may work for some households but be unrealistic for others. Consider your complete financial situation before selecting a percentage.
Is investing every month better than waiting?
Regular investing can help establish discipline and reduce the temptation to time the market. However, investing always involves risk, and money needed for short-term expenses may be better kept in an appropriate savings account.
How much should I invest if I have debt?
It depends on the debt’s interest rate, your emergency savings, and available retirement-plan benefits. High-interest debt repayment often deserves priority.
Final Thoughts
The right amount to invest each month is not the highest number you can temporarily afford. It is an amount that supports your long-term goals while leaving enough money for essential expenses, debt obligations, and emergencies.
Start with your budget, choose a sustainable contribution, and revisit the amount as your circumstances change.
Small, consistent steps can be more useful than an ambitious plan you cannot maintain.
Sources and Further Reading
- Investor.gov — Compound Interest Calculator
- Consumer Financial Protection Bureau — An Essential Guide to Building an Emergency Fund
- IRS — Retirement Plans
Disclaimer: This article is for general educational purposes and does not constitute personalized financial, investment, or tax advice. All return examples are hypothetical.
Leave a Reply